
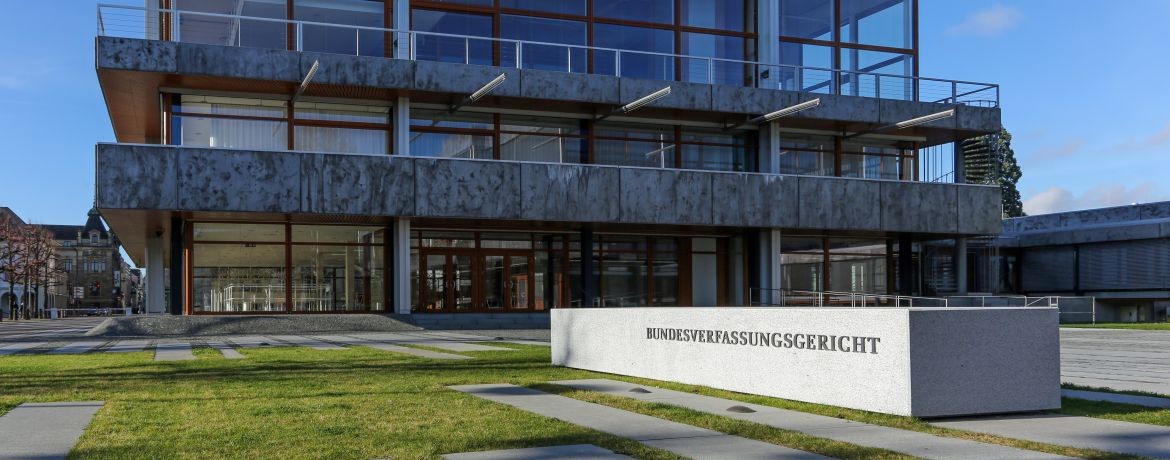
The inheritance tax relief available for business assets is once again under scrutiny. On 13 October 2026, the German Federal Constitutional Court heard a constitutional complaint brought by an heir to private assets (case no. 1 BvR 804/22). For business-owning families, the case raises important questions about the reliability of existing succession planning arrangements.
Constitutional complaint: inheritance tax relief for business assets under review
The claimant inherited only private assets from his aunt, including a securities portfolio and real estate. On an inheritance of around €250,000, he paid approximately €47,000 in inheritance tax.
His claims were unsuccessful before the fiscal courts, most recently before the German Federal Fiscal Court (BFH, decision of 17 January 2022, case no. II B 49/21). He argued that the relief provisions for business assets under the German Inheritance and Gift Tax Act were unconstitutional because substantial business assets may receive extensive tax relief, whereas inherited private assets are generally taxed in the ordinary way. In his view, this infringes both the principle of equality and the principle of the social welfare state.
Before the Federal Constitutional Court in Karlsruhe, he is likewise challenging the fact that recipients of business assets may benefit from extensive or complete tax relief, while private assets are taxed without comparable relief.
The challenge indirectly concerns, in particular, sections 13a, 13b, 13c, 19a and 28a ErbStG, as well as section 203 BewG.
The rules now under review are themselves a response to an earlier decision from Karlsruhe.
In its judgment of 17 December 2014, case no. 1 BvL 21/12, the Federal Constitutional Court accepted in principle that business assets could receive preferential inheritance tax treatment in order to protect businesses and jobs. However, it rejected the structure of the rules then in force. In particular:
- large acquisitions could qualify for relief without any needs test;
- businesses with up to 20 employees were exempt from the payroll requirement; and
- administrative assets amounting to up to 50% of the business assets did not prevent relief.
The 2016 reform tightened the rules on administrative assets and, for acquisitions exceeding €26 million, introduced a choice between the reduction model under section 13c ErbStG and the needs-based relief test under section 28a ErbStG.
Under the latter, inheritance tax is waived to the extent that the recipient cannot pay it from their available assets. Available assets are deemed to include half of the non-privileged assets acquired together with the business assets as well as half of the recipient’s existing non-privileged assets.
According to the German Federal Statistical Office, around €3.7 billion in tax was waived under these rules in 2025 alone, of which € 3.4 billion related to gifts.
What the oral hearing revealed
At the beginning of the hearing, court President Stephan Harbarth emphasised that equal taxation affects “the sense of justice of many people in our country in a particularly significant way”. However, the court must decide only on the constitutionality of the statutory provisions.
One notable point is that the Senate expressed doubts about the admissibility of the complaint insofar as it relies on fundamental freedoms and procedural rights. The strongest aspect of the complaint appears to be the alleged infringement of the general principle of equality under Article 3(1) of the German Constitution.
The Senate heard evidence from around twenty experts.
Several economists acknowledged that there is a lack of reliable data on the actual effects of the business asset relief rules. Leading tax law experts generally considered the standard relief under section 13a ErbStG to be constitutional in principle. The needs-based relief test attracted considerably more criticism. It focuses on the recipient’s ability to pay rather than directly on protecting the business and is considered susceptible to tax planning arrangements. Critics referred, for example, to transfers to children with little or no personal wealth or to newly established family foundations.
The €26 million acquisition threshold and the distinction between qualifying business assets and administrative assets were also criticised.
The German Federal Government defended the current framework as a constitutionally compliant implementation of the requirements laid down by the court in 2014.
Current implications for business succession planning and advisory practice
No date has yet been set for the judgment to be delivered. A decision is expected within the coming months, potentially around the end of 2026 or the beginning of 2027, or during the course of 2027.
Based on the course of the hearing, it appears unlikely that the relief for business assets will be struck down in its entirety. Targeted objections to individual provisions appear more realistic, particularly in relation to section 28a ErbStG. Possible consequences could include:
- a declaration that individual provisions are incompatible with the constitution
- their continued application for a limited transitional period and
- an instruction to the legislature to amend the law.
Irrespective of the court’s decision, a political debate about reform is already emerging. The SPD has already proposed a model involving a €5 million business allowance.
A further case is also pending before the Federal Constitutional Court under case no. 1 BvF 1/23. On the previous day, the Senate heard Bavaria’s application for abstract judicial review, concerning tax allowances, tax rates, the valuation of real estate and legislative competence.
Should business succession be implemented before the court rules?
Until the court delivers its decision, the existing law remains applicable. However, protection of legitimate expectations is limited.
In 2014, the court held that, in relation to excessive tax planning arrangements, a new statutory regime could exceptionally take effect retroactively from the date on which the judgment was delivered.
Business-owning families planning to transfer business assets should therefore review now whether implementation before the judgment is delivered may be appropriate.
The review should cover in particular:
- the administrative asset test;
- payroll requirements;
- minimum holding periods;
- the corporate-law requirements for the advance deduction under section 13a(9) ErbStG; and
- clawback and tax clauses.
Particularly in the case of large acquisitions, inheritance law and tax planning should be coordinated carefully, and alternatives to the needs-based relief test should be modelled and compared.
You can find out more about how we support clients in this area on our page on business and wealth succession.
This article is intended for general information purposes only and does not constitute individual legal or tax advice. We would be pleased to assist you with any legal or tax-related questions concerning business asset relief, business succession and inheritance tax.
Do you have any questions about inheritance tax relief provisions?
Please feel free to get in touch. I would be pleased to answer your questions on this topic. Simply arrange an appointment using the booking options shown alongside.
Yours sincerely,
Leon Feyler
Your ACCONSIS contact
Leon Feyler
Lawyer
Authorised signatory of ACCONSIS
Service phone
+49 89 54 71 43
or via email
l.feyler@acconsis.de
FAQ: answers to frequently asked questions on this topic
1. What was the Federal Constitutional Court hearing on 13 October 2026 about?
The hearing concerned the constitutional complaint of an heir to private assets in case 1 BvR 804/22. The claimant argues that the inheritance tax relief available for business assets under sections 13a et seq. and 28a ErbStG breaches Article 3 of the German Constitution, which guarantees equality before the law, because recipients of private assets do not receive comparable relief.
2. Does the inheritance tax relief for business assets still apply?
Yes. Until the Federal Constitutional Court issues its decision and any new legislation is introduced, the existing inheritance tax rules remain in force. If the court finds individual provisions unconstitutional, a retroactive legislative amendment aimed at excessive tax planning arrangements may be possible from the date on which the judgment is delivered.
3. When is a judgment expected?
No date for delivery of the judgment has yet been announced. A decision is expected within the next few months, potentially around the end of 2026 or the beginning of 2027, or during the course of 2027.
4. What should business-owning families do now?
Planned transfers of business assets should be reviewed now and, where appropriate, implemented before the court delivers its judgment. Particular attention should be paid to administrative assets, the company’s constitutional documents and any clawback provisions.
Image source: adobe stock


